Cash App
Block, Inc.
- 4.7
- 447.54K Reviews
- 100.00M
- Downloads
- Free
- Price
Screenshots
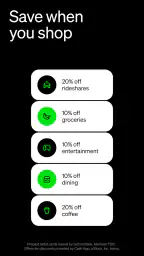
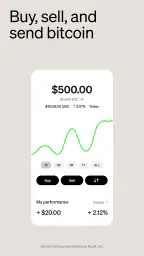
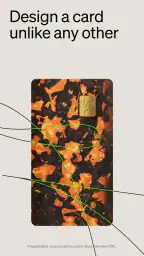
Cash App Pros and Cons
Pros
- Easy to use interface.
- Fast money transfers.
- No fees for basic services.
- Supports Bitcoin transactions.
- Cashback offers available.
Cons
- Limited international use.
- Requires internet connection.
- No joint accounts feature.
- Customer service can be slow.
- Limited investment options.
 Analysis by All-app
Most of my day-to-day use of Cash App has been straightforward, but payment apps can be confusing when something doesn’t go as expected. A payment may appear to be waiting, a recipient may not be easy to identify, or a card transaction may not look the way you thought it would. I’ve found that the best first step is to slow down and check the details on screen before trying the same action again. That small pause can prevent a duplicate payment or a second request when the first one is still being processed.
When a transfer does not look finished
If I’m unsure whether money has gone through, I check the activity for that specific transaction rather than immediately sending it again. I also confirm the recipient’s details and the amount before taking another step. This is especially useful when splitting a bill: a quick glance at the transaction record is more dependable than relying on memory or a message thread. If the status is unclear, I avoid making a second payment until I understand what happened.
A familiar name or profile image is not enough reason to assume I have selected the right person. Before confirming a transfer, I compare the identifying details shown in the app with what the recipient has shared with me. For a first payment, I prefer to verify those details directly with the person. That extra check is a simple habit, but it matters when a payment is meant to reach one particular friend rather than someone with a similar name.
Small setup checks that prevent bigger headaches
Before using a finance app for an important payment, I make sure I can sign in and recognize the contact information associated with my account. I also take a moment to understand where the app displays transaction activity, how its security lock is set, and which balance or payment method I am choosing. These checks are more useful than waiting until I’m standing at a checkout or trying to settle a shared bill with friends.
I treat payment details as private, even when I’m dealing with people I know. I don’t share sign-in codes or passcodes in a chat, and I’m cautious about requests that pressure me to send money immediately. If a message claims to come from someone I trust, I confirm through a separate conversation before paying. Cash App can make a transfer convenient, but convenience does not replace checking that a request is genuine.
Making the app fit a real routine
Cash App is most useful to me when I have a clear, limited purpose for it: paying a friend back, collecting a shared expense, or keeping a dedicated balance for everyday spending. I would not assume that every feature suits every user. Someone who wants a traditional bank account as their main financial home may prefer to compare banking services carefully, while a person who simply needs a practical way to settle small personal payments may appreciate the quicker, more focused routine here.
That distinction also helps me decide when not to use it. For a large or unfamiliar payment, I’m more comfortable using a method with protections and processes that fit the transaction, rather than choosing a peer-to-peer transfer just because it is convenient. I also wouldn’t treat buying Bitcoin as a casual extension of splitting dinner: cryptocurrency can fluctuate in value, so I’d only explore it after understanding the risks and deciding it fits my goals.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
Have you ever found yourself in a pinch and needed to send or receive money quickly? Well, let me tell you about my experience with the Cash App, a peer-to-peer payment service that has saved me more times than I can count.
Simplifying Money Transfers
So, here's the deal: Cash App makes sending and receiving money as easy as pie. All you need is an email address or a phone number, and you’re good to go. I remember the first time I used it to split a dinner bill with friends. Just a few taps on my phone, and voila! My part of the bill was settled without any awkward cash exchanges.
What Sets It Apart?
I’ve tried other payment apps before, but there’s something about Cash App that just clicks. Maybe it’s the sleek and straightforward interface that doesn’t overwhelm you with too many options. Or perhaps it’s the added feature of being able to buy and sell Bitcoin right from the app. Yes, you read that right! You can dabble in cryptocurrency without having to switch platforms.
Another cool feature is the Cash Card, a customizable debit card linked directly to your Cash App balance. You can use it at any store that accepts Visa. Personalizing my Cash Card with funky designs was surprisingly fun and made the experience feel extra special.
Security and Convenience
Now, I know what you’re thinking: “Is it safe?” I had the same question. But rest assured, Cash App has several security features to keep your funds secure. They use encryption and fraud detection technology to protect users. Plus, you can enable security lock settings to require a passcode for every transaction.
Convenience is another big win for this app. Need to pay your share of the rent or an IOU to a friend? You can do it instantly. And if you’re the kind of person who likes earning rewards, you’ll love the Boost feature. It offers discounts at various retailers when you use your Cash Card. I’ve saved quite a bit on coffee runs thanks to this!
Where it fits among finance apps
Cash App is a free finance app from Block, Inc., and its broad mix of money tools is unusual for something that began in my routine as a way to settle up with friends. It has a 4.7 average from around four million ratings and more than 100 million installs, which tells me it has reached far beyond a small circle of occasional users. It is rated for everyone, though I’d still expect younger users to involve a trusted adult when making financial decisions. The app first appeared on October 15, 2013, and version 5.28.1 is listed for devices running OS 10 or later.
Compared with a bank’s own app, I see Cash App as a more focused choice for person-to-person payments and a few connected money activities, not automatically as a replacement for every banking need. Compared with a wallet that only handles checkout, it gives me more reasons to return: I can use it to move money between people and explore Bitcoin in the same place. That breadth is convenient, but it also means I should pay attention to which part of the app I’m using. Sending a friend money, spending from a card, and making an investment are different decisions, even if they sit behind one familiar interface.
A practical routine, not a set-and-forget account
One realistic use is a shared grocery run. I might pay at the shop, then ask a housemate to send their part later; when the payment arrives, I check the activity and make sure it matches what we agreed. For recurring household costs, I would still keep a separate note of who owes what instead of assuming the payment history alone explains the whole arrangement. The app can make the transfer simpler, but it cannot settle disagreements about the amount or replace clear communication.
I also think about the order of operations. Before asking someone to pay me, I agree on the amount and the reason in the same conversation. Before spending with the Cash Card, I check that I’m using the intended balance. Before exploring Bitcoin, I pause to consider whether I’m comfortable with price changes. Those quick distinctions are practical safeguards: they keep ordinary payments from getting mixed up with spending choices or investment risk.
If a payment or card purchase needs a second look
When a card purchase does not match what I expected, I start by checking the transaction details and comparing them with the receipt or the amount I agreed to pay. If the mismatch is still confusing, I avoid guessing or making another payment to “correct” it until I know what the original entry represents. For a person-to-person transfer, I use the activity record in the same way and confirm the intended recipient before acting again. Keeping a clear record of the conversation and receipt can make it easier to explain the issue if I need to seek help through the app.
Some problems are not caused by the app itself. A recipient may have shared the wrong contact detail, a request may have come from an impersonator, or a purchase amount may differ from what I remembered. I try to separate those possibilities from a genuine account or transaction problem rather than assuming every surprise is a technical failure. If the screen does not give me enough clarity, I stop and use the app’s own support route instead of trusting an unsolicited message that offers to fix the account.
Who will appreciate it, and who may prefer something else
I’d recommend Cash App to someone who regularly settles personal expenses with people who are comfortable using it, wants a simple place for those transfers, and values having additional money tools close at hand. It can also suit someone who likes managing a separate spending routine with a linked card. The benefit is less about replacing every financial service and more about reducing the friction of a familiar set of everyday tasks.
I would steer a person toward comparing other options if they need a traditional bank to be the center of their finances, want a payment method designed for purchases from unfamiliar sellers, or prefer not to keep investing tools beside routine transfers. A bank app may fit better for broader account management; a payment method with transaction-specific buyer protections may be the more sensible choice for an unfamiliar purchase. The right alternative depends on what could go wrong and what support or protections matter for that particular payment.
What I check before relying on it
People often wonder whether they need to use every feature to benefit from the app. I don’t think so. A person can keep their use narrow and treat transfers as the main reason to open it, while leaving Bitcoin or card spending aside if those do not fit. The more useful question is whether the people they need to pay or collect from can use the same service comfortably, and whether its payment flow suits the amounts and situations involved.
Another sensible question is what to do when a transfer seems delayed or unclear. My approach is to inspect the transaction record, verify the recipient and amount, and avoid repeating the payment while the first one remains uncertain. If a sign-in or account issue prevents that check, I use the app’s official in-app help rather than sharing security information with anyone who contacts me unexpectedly. I also keep expectations realistic: an easy interface can make routine actions quick, but it cannot guarantee that every recipient, purchase, or network situation will behave exactly as I expect.
It is also worth asking whether the app is a good fit for a person who is new to money management. I think it can be approachable for basic peer payments, but I would encourage a new user to learn what each balance and feature represents before moving significant funds or making an investment. Starting with one low-stakes use, checking the resulting activity, and setting a security lock creates a calmer way to learn than exploring every tool at once.
Final Thoughts
Overall, my experience with the Cash App has been nothing short of fantastic. It’s intuitive, reliable, and packed with useful features that cater to both casual users and those diving into the world of cryptocurrency. If you’re looking for a hassle-free way to manage your transactions and even save a few bucks along the way, give it a shot. You won’t be disappointed!
My more measured recommendation is to try it when person-to-person payments are a real part of your routine, then keep the scope of use clear. I like the convenience, the accessible layout, and the option to handle different money tasks without jumping between several apps. I also think the best experience comes from checking recipient details, treating Bitcoin as an investment rather than a novelty, and choosing another payment method when a transaction needs protections better suited to an unfamiliar seller.
Frequently Asked Questions
What is Cash App and how does it work?
Cash App is a mobile payment service that allows you to send and receive money instantly using your smartphone. Once you download the app, you can link your bank account or credit card to it. Users can transfer funds to other Cash App users, pay for purchases, and even invest in stocks or Bitcoin. It's a versatile app for managing personal finances conveniently.
Is Cash App safe to use for transactions?
Yes, Cash App is considered safe for transactions as it employs encryption and security measures to protect user data. It also offers additional security features like PIN entry, touch ID, or face recognition for added protection. However, users should always be cautious and ensure they are sending money to trusted recipients to avoid scams.
Are there fees associated with using Cash App?
Cash App does not charge fees for basic services like sending or receiving money via linked bank accounts. However, there may be fees for certain transactions, such as instant transfers to a debit card or transactions made with a credit card. Users should review the app’s fee structure to understand any costs that may apply.
Can I use Cash App internationally?
Currently, Cash App is only available for users in the United States and the United Kingdom. Users in these countries can send and receive money to and from other users within these regions. It does not support international transactions outside of these countries, so users should consider this limitation if they need global payment solutions.
What should I do if I encounter an issue with my Cash App account?
If you experience any problems with your Cash App account, the best course of action is to contact Cash App support through the app. They offer in-app customer service where you can report issues, get help with transactions, or resolve account-related queries. It’s important to keep all transaction records and communication for reference.